



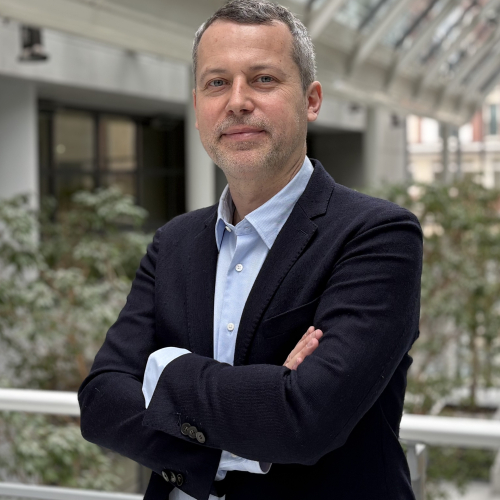
Mieszko Mazur is Associate Professor of Finance at EMLV Business School. He holds a PhD in Finance from Tilburg University. His primary research focus is on financial technology (FinTech) including blockchains, cryptocurrencies, decentralized finance (DeFi), stablecoins, tokenization, and non-fungible tokens (NFT). His second area of expertise is in empirical corporate finance and corporate governance. His work has appeared in numerous internationally recognized peer-reviewed journals, including the Journal of Financial Markets, Journal of Macroeconomics, European Journal of Financial Management, Journal of Alternative Investments, International Review of Financial Analysis, and Journal of Applied Corporate Finance, among others. His work on cryptocurrencies has received extensive coverage in the international popular media. He has held many visiting positions including at the New York University Stern School of Business, University of Technology Sydney, University of the New South Wales, Da Nang University of Economics, and University of Texas at Austin.


Mieszko Mazur; Efstathios Polyzos
Tokenized stocks and tracking errors: Evidence on pricing efficiency Journal Article
In: Finance Research Letters, vol. 106, no. 106, pp. 110201, 2026.
@article{mazur_4464,

title = {Tokenized stocks and tracking errors: Evidence on pricing efficiency},

author = {Mieszko Mazur and Efstathios Polyzos},

url = {https://doi.org/10.1016/j.frl.2026.110201},

year  = {2026},

date = {2026-09-01},

journal = {Finance Research Letters},

volume = {106},

number = {106},

pages = {110201},

abstract = {Tokenized stocks emerge as an innovative gateway to the ownership of foreign assets that otherwise would not be accessible to many investors worldwide. In this paper, we investigate whether tokenized stocks are priced efficiently based on the analysis of tracking errors that may arise between tokenized and traditional stocks. We find that tracking errors increase with return volatility, market-wide uncertainty and weaker alignment between token and equity returns. Moreover, mis-tracking is more pronounced for firms with higher valuations, greater market risk exposure, and elevated short-selling activity.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Dang Man; Puwanenthiren Premkanth; Mieszko Mazur; Hoang Viet; Sivathaasan Nadarajah; Nguyen Thieu
Firm complexity and credit ratings Journal Article
In: International Review Of Financial Analysis, vol. 104, no. Part A, pp. 104267, 2025.
@article{man_4312,

title = {Firm complexity and credit ratings},

author = {Dang Man and Puwanenthiren Premkanth and Mieszko Mazur and Hoang Viet and Sivathaasan Nadarajah and Nguyen Thieu},

url = {https://doi.org/10.1016/j.irfa.2025.104267},

year  = {2025},

date = {2025-08-01},

journal = {International Review Of Financial Analysis},

volume = {104},

number = {Part A},

pages = {104267},

abstract = {This paper examines the effect of firm complexity on credit ratings. Using a sample of U.S. non-financial firms and the state-of-the-art measure of firm complexity, we document a significantly negative relation between firm complexity and credit ratings, suggesting that rating agencies assign significantly lower credit score to more complex firms. Our results remain robust to alternative specifications and various endogeneity checks. Moreover, we find that the negative effect on credit ratings becomes weaker in more transparent and better-governed firms. Finally, we show that the effect is more pronounced during periods of high policy uncertainty. Overall, our paper provides a better understanding of complex firms and highlights the importance of transparency that enhances creditworthiness and mitigates credit risk.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Thi Thuy Anh Vo; Nguyen Tram Anh Tran; Mieszko Mazur
Institutional ownership and stock liquidity during the COVID-19 crisis: a global perspective Journal Article
In: Review of Behavioral Finance, vol. 17, no. 3, pp. 482-498, 2025.
@article{vo_4341,

title = {Institutional ownership and stock liquidity during the COVID-19 crisis: a global perspective},

author = {Thi Thuy Anh Vo and Nguyen Tram Anh Tran and Mieszko Mazur},

url = {https://doi.org/10.1108/RBF-04-2024-0107},

year  = {2025},

date = {2025-05-01},

journal = {Review of Behavioral Finance},

volume = {17},

number = {3},

pages = {482-498},

abstract = {This study represents the first comprehensive exploration of how the COVID-19 crisis has influenced the relationship between institutional ownership and stock liquidity within an international context. By examining this association across diverse markets, the study aims to shed light on the dynamic interplay between institutional investors and stock liquidity during one of the most disruptive global events in modern financial history.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Efstathios Polyzos
Spot Bitcoin ETFs: The Effect of Fund Flows on Bitcoin Price Formation Journal Article
In: Journal of Alternative Investments, vol. 27, no. 4, pp. 110-123, 2025.
@article{mazur_4315,

title = {Spot Bitcoin ETFs: The Effect of Fund Flows on Bitcoin Price Formation},

author = {Mieszko Mazur and Efstathios Polyzos},

url = {http://dx.doi.org/10.2139/ssrn.5452994},

year  = {2025},

date = {2025-04-01},

journal = {Journal of Alternative Investments},

volume = {27},

number = {4},

pages = {110-123},

abstract = {Inflows to the newly established bitcoin exchange-traded funds (ETFs) surpassed $20 billion in the first several weeks of trading and are considered record-high by ETF standards. In this article, we provide an early examination of the bitcoin spot ETFs listed on US exchanges and their effect on bitcoin price formation. We establish several empirical facts: 1) daily capital flows to new spot bitcoin ETFs exceed $500 million or roughly 10,000 bitcoins, and surpass bitcoin mining production by the factor of 5; 2) net flows to ETFs are a strong positive predictor of bitcoin price levels with the R-squared of 95%; 3) most bitcoin price changes occur outside ETF trading hours; 4) an increase in bitcoin price leads to abnormal ETF trading volume; 5) inflows to bitcoin ETFs correlate with outflows from gold ETFs. Overall, during the period studied, capital flows to spot-bitcoin-ETFs emerge as a dominant single factor predicting bitcoin valuation effects.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Miguel Vega; Mieszko Mazur; Martin Quinn
Successful implementation of employee-driven innovation in a public healthcare organization Journal Article
In: Recherches en Sciences de Gestion, vol. 164, no. 5, pp. 41-64, 2024.
@article{vega_4318,

title = {Successful implementation of employee-driven innovation in a public healthcare organization},

author = {Miguel Vega and Mieszko Mazur and Martin Quinn},

url = {https://doi.org/10.3917/resg.164.0041},

year  = {2024},

date = {2024-12-01},

journal = {Recherches en Sciences de Gestion},

volume = {164},

number = {5},

pages = {41-64},

abstract = {This case study explores bottom-up employee innovation and organizational learning in a Spanish public hospital, highlighting how a new surgery enhances knowledge sharing and performance results. Key facilitators (support, coordination, indicators, cooperation) and barriers (collegial views, rules) are identified, contributing to research on the positive impact of employee-driven innovation in professional and bureaucratic public settings with limited resources.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; David Iheke Okorie; Elie I. Bouri
NFTs versus conventional cryptocurrencies: A comparative analysis of market efficiency around COVID-19 and the Russia-Ukraine conflict Journal Article
In: Quarterly Review Of Economics And Finance, vol. 95, pp. 126-151, 2024.
@article{mazur_4317,

title = {NFTs versus conventional cryptocurrencies: A comparative analysis of market efficiency around COVID-19 and the Russia-Ukraine conflict},

author = {Mieszko Mazur and David Iheke Okorie and Elie I. Bouri},

url = {http://dx.doi.org/10.1016/j.qref.2024.03.001},

year  = {2024},

date = {2024-06-01},

journal = {Quarterly Review Of Economics And Finance},

volume = {95},

pages = {126-151},

abstract = {This paper examines the efficiency of the market for non-fungible tokens (NFTs) against the backdrop of the market for fungible tokens (FTs) that includes Bitcoin and Ethereum. We focus on two important shocks: the outbreak of COVID-19 and the Russia-Ukraine conflict. To this end, we employ martingale difference sequence and conditional heteroscedasticity estimation techniques. We find that the efficiency of both markets fluctuates in time and the aforementioned shocks have a profound effect on FTs and NFTs. More specifically, we find that the effect of COVID-19 is heterogeneous for both markets, whereas that of the Russian invasion of Ukraine is homogenous for NFTs but heterogeneous for FTs.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ettore Croci; Mieszko Mazur; Galla Salganik-Shoshan
Coordinated monitoring and mergers and acquisitions Journal Article
In: European Financial Management, vol. 30, no. 3, pp. 1422-1459, 2024.
@article{croci_4324,

title = {Coordinated monitoring and mergers and acquisitions},

author = {Ettore Croci and Mieszko Mazur and Galla Salganik-Shoshan},

url = {https://doi.org/10.1111/eufm.12449},

year  = {2024},

date = {2024-06-01},

journal = {European Financial Management},

volume = {30},

number = {3},

pages = {1422-1459},

abstract = {This paper shows that coordinated monitoring by institutional investors affects how firms behave in the M&A market. We employ the spatial dimension of geographic links between major institutions as a proxy for interaction and information exchange?a process that determines the effectiveness of investor monitoring over firm management. Using data over the last 30 years, we show that the returns to acquiring shareholders are significantly higher, and M&A activity is significantly more intense when institutions coordinate better their monitoring efforts. Our results are robust to series of tests to gauge their sensitivity to different model specifications and estimation procedures.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Efstathios Polyzos; Ghulame Rubbaniy; Mieszko Mazur
Efficient Market Hypothesis on the blockchain: A social?media?based index for cryptocurrency efficiency Journal Article
In: Financial Review (US), vol. 59, no. 3, pp. 807-829, 2024.
@article{polyzos_4316,

title = {Efficient Market Hypothesis on the blockchain: A social?media?based index for cryptocurrency efficiency},

author = {Efstathios Polyzos and Ghulame Rubbaniy and Mieszko Mazur},

url = {https://doi.org/10.1111/fire.12387},

year  = {2024},

date = {2024-03-01},

journal = {Financial Review (US)},

volume = {59},

number = {3},

pages = {807-829},

abstract = {This paper proposes the use of social media as a proxy for financial information. Using an extended sample of 53,580,759 tweets and employing text analysis tools (Latent Dirichlet Allocation and Term Frequency-Inverse Document Frequency), we determine the information being exchanged on any given day. We train machine-learning classifiers and forecast crypto price movements for more than 8000 cryptocurrencies and gauge market efficiency through successful forecasts based on public information. We propose various metrics of market efficiency for cryptocurrency assets and demonstrate that market efficiency is higher during the first 6 months after the Initial Coin Offering. We also examine the efficiency behavior of individual currencies during crisis periods.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Thi Thuy Anh Vo; Mieszko Mazur
Institutional ownership and stock return volatility during the COVID-19 crisis: An international evidence Journal Article
In: Finance Research Letters, vol. 58, no. Part D, pp. 104669, 2023.
@article{vo_4319,

title = {Institutional ownership and stock return volatility during the COVID-19 crisis: An international evidence},

author = {Thi Thuy Anh Vo and Mieszko Mazur},

url = {https://doi.org/10.1016/j.frl.2023.104669},

year  = {2023},

date = {2023-12-01},

journal = {Finance Research Letters},

volume = {58},

number = {Part D},

pages = {104669},

abstract = {Using a sample of 39 countries from 2010 through 2021, we find that while institutional holdings have the stabilizing effect during the normal (non-crisis) period, they appear to move stock prices away from fundamentals during the COVID-19 crisis. Furthermore, the impact of foreign and domestic institutions is not homogenous. We also find that institutional investors help reduce stock return volatility in countries more strongly affected by the COVID-19 crisis. Finally, our results indicate that investor protection moderates the impact of institutional holdings on stock return volatility in both pre- and crisis periods.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Thi Hong An Thai; Thi Thuy Anh Vo; Mieszko Mazur
COVID-19 and investment-cash flow sensitivity: A cross-country analysis Journal Article
In: Research In International Business And Finance, vol. 66, pp. 102014, 2023.
@article{thai_4320,

title = {COVID-19 and investment-cash flow sensitivity: A cross-country analysis},

author = {Thi Hong An Thai and Thi Thuy Anh Vo and Mieszko Mazur},

url = {http://dx.doi.org/10.1016/j.ribaf.2023.102014},

year  = {2023},

date = {2023-10-01},

journal = {Research In International Business And Finance},

volume = {66},

pages = {102014},

abstract = {This study investigates investment-cash flow sensitivity during the COVID-19 economic crisis. Using an international sample of publicly listed firms, we find that the sensitivity of capital expenditures to cash flows is significantly reduced during the crisis. When we split the sample into strongly and weakly affected countries, we find that firms in countries affected more seriously by COVID-19 exhibit lower investment responsiveness to cash flows. We further find that investment-cash flow sensitivity is diminished when government aid is greater, firms have more cash on hand, and investment opportunities decline. Our results survive a host of robustness checks. This study contributes to the discussion on the impact of COVID-19 on corporate policies within an international framework.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Miguel Vega
Football and Cryptocurrencies Journal Article
In: Journal of Alternative Investments, vol. 26, no. 1, pp. 23-38, 2023.
@article{mazur_4327,

title = {Football and Cryptocurrencies},

author = {Mieszko Mazur and Miguel Vega},

url = {http://dx.doi.org/10.3905/jai.2023.1.188},

year  = {2023},

date = {2023-08-01},

journal = {Journal of Alternative Investments},

volume = {26},

number = {1},

pages = {23-38},

abstract = {This article investigates the emerging segment of the cryptocurrency market related to football fan tokens (FFTs)?digital assets used for engagement with professional football clubs around the world. More specifically, the authors study the investability of FFTs from the perspective of risk and return. They find that FFTs generate a whopping 150% return on the first trading day. This return is significantly larger if the FFT market cap is higher, the FFT offer price is lower, the football team displays better historical performance, and the team is located in a relatively small metropolitan area with a high GDP per capita. They also find that in the long run, FFTs severely underperform all major crypto benchmarks, including NFT, DeFi, Meme, and bitcoin. Moreover, the returns to FFTs tend to be highly volatile (160% annualized). Intriguingly, they show that the real-life performance of football teams does not affect the contemporaneous market performance of their FFTs.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Man Dang; Thi Thuy Anh Vo
Dividends and share repurchases during the COVID?19 economic crisis Journal Article
In: Journal Of Financial Research, vol. 46, no. 2, pp. 291-314, 2023.
@article{mazur_4321,

title = {Dividends and share repurchases during the COVID?19 economic crisis},

author = {Mieszko Mazur and Man Dang and Thi Thuy Anh Vo},

url = {https://doi.org/10.1111/jfir.12324},

year  = {2023},

date = {2023-07-01},

journal = {Journal Of Financial Research},

volume = {46},

number = {2},

pages = {291-314},

abstract = {In this article, we examine dividends and share repurchases of S&P 1500 firms during the COVID-19 crisis characterized by the stock market crash and a relatively quick stock price recovery propelled by technology stocks. We find that the great majority of firms either maintain or increase the level of dividends during the crisis period. Yet, the relation between the dividend payout and reported earnings is negative and significant. This relation also holds for other types of payouts, including share repurchases and special dividends. Moreover, we find that both forecasted and realized earnings of up to 1 year into the future are negatively associated with current dividends, implying that existing payout policies are unsustainable in the longer term. Surprisingly, the difference-in-differences test shows that firms strongly affected by the COVID-19 crisis have higher dividend payouts (relative to net earnings) compared to unaffected firms. The same test indicates that strongly affected firms significantly reduce repurchases.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
K. Peren Arin; Kevin Devereux; Mieszko Mazur
Taxes and firm investment Journal Article
In: Journal Of Macroeconomics, vol. 76, pp. 103517, 2023.
@article{arin_4322,

title = {Taxes and firm investment},

author = {K. Peren Arin and Kevin Devereux and Mieszko Mazur},

url = {https://doi.org/10.1016/j.jmacro.2023.103517},

year  = {2023},

date = {2023-06-01},

journal = {Journal Of Macroeconomics},

volume = {76},

pages = {103517},

abstract = {We investigate the firm-level investment response to unanticipated narrative shocks to average personal and corporate tax rates using a universal micro dataset of publicly-traded U.S. firms for the post-1976 period. Using local projections, we show that: (i) corporate tax shocks have significant effects on investment while personal tax shocks do not; (ii) corporate income tax responses are negative overall, and this result is driven by smaller firms who face larger borrowing constraints, especially when the accompanying monetary policy is contractionary or output gap is slack; (iii) there is some evidence of positive personal income tax responses during monetary contractions by dividend-paying firms, which is consistent with the recent literature.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Thi Thuy Anh Vo; Mieszko Mazur
The effect of investor protection on firm riskiness and performance during the COVID-19 economic crisis Journal Article
In: Applied Economics Letters, vol. 30, no. 6, pp. 724-734, 2023.
@article{vo_4323,

title = {The effect of investor protection on firm riskiness and performance during the COVID-19 economic crisis},

author = {Thi Thuy Anh Vo and Mieszko Mazur},

url = {https://doi.org/10.1080/13504851.2021.2016581},

year  = {2023},

date = {2023-06-01},

journal = {Applied Economics Letters},

volume = {30},

number = {6},

pages = {724-734},

abstract = {This paper examines whether differences in the quality of investor protection between countries affect firm riskiness and firm performance during the COVID-19 economic downturn. Using a large cross-country dataset and a broad variety of controls measured at the state and firm level, we find that jurisdictions that offer stronger investor protection experience significantly lower volatility and better performance during the pandemic. This effect is amplified in countries strongly affected by COVID-19. Our results contribute to the ongoing debate in the finance literature about the impact of the quality of investor protection on corporate behaviour and performance.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Man Dang; Premkanth Puwanenthiren; Manh Toan Nguyen; Viet Anh Hoang; Mieszko Mazur; Darren Henry
Does managerial tone matter for stock liquidity? Evidence from textual disclosures Journal Article
In: Finance Research Letters, vol. 48, pp. 102917, 2022.
@article{dang_4325,

title = {Does managerial tone matter for stock liquidity? Evidence from textual disclosures},

author = {Man Dang and Premkanth Puwanenthiren and Manh Toan Nguyen and Viet Anh Hoang and Mieszko Mazur and Darren Henry},

url = {https://doi.org/10.1016/j.frl.2022.102917},

year  = {2022},

date = {2022-08-01},

journal = {Finance Research Letters},

volume = {48},

pages = {102917},

abstract = {This study investigates the effect of managerial tone on stock liquidity using a sample of U.S.-listed firms over the 1994-2019 period. We find that firms with SEC filings exhibiting more positive managerial tone experience higher stock liquidity. Our findings remain unchanged after controlling for firm fixed effects, investor sentiment, firm size differences and using alternative variable approaches. Further, we identify that the relationship is less pronounced during times of high policy uncertainty measured by EPU and presidential elections. Overall, this paper provides evidence that the management tone in SEC filings has price discovery and efficiency implications for investor trading decisions.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Man Dang; Darren Henry; Hong An Thai; Xuan Vinh Vo; Mieszko Mazur
Does policy uncertainty predict the death of M&A deals? Journal Article
In: Finance Research Letters, vol. 46, no. PART B, pp. 102489, 2022.
@article{dang_4328,

title = {Does policy uncertainty predict the death of M&A deals?},

author = {Man Dang and Darren Henry and Hong An Thai and Xuan Vinh Vo and Mieszko Mazur},

url = {https://doi.org/10.1016/j.frl.2021.102489},

year  = {2022},

date = {2022-05-01},

journal = {Finance Research Letters},

volume = {46},

number = {PART B},

pages = {102489},

abstract = {Using a comprehensive sample of U.S. M&A deals from 2000 through 2020, we examine whether the magnitude of policy uncertainty can explain the likelihood of deal cancellation. Consistent with our conjecture, we find that policy uncertainty is a significant predictor of the death of deals. Moreover, we find evidence of a negative association between policy uncertainty and the target firm stock price levels, implying that the market also incorporates the consequences of policy uncertainty into target valuation and bid likelihood outcomes. Altogether, our findings add to the understanding of the interplay between policy uncertainty and external investments through M&A.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur
Misperceptions of Bitcoin Volatility Journal Article
In: Journal of Alternative Investments, vol. 24, no. 4, pp. 33-44, 2022.
@article{mazur_4326,

title = {Misperceptions of Bitcoin Volatility},

author = {Mieszko Mazur},

url = {http://dx.doi.org/10.3905/jai.2022.1.153},

year  = {2022},

date = {2022-04-01},

journal = {Journal of Alternative Investments},

volume = {24},

number = {4},

pages = {33-44},

abstract = {Bitcoin market capitalization recently surpassed $1 trillion. While popular belief holds that a key characteristic of bitcoin is its excessive volatility, this article provides evidence that this is largely a misperception. We show that bitcoin return fluctuations are lower than those of roughly 900 stocks in the S&P1500 and 190 stocks in the S&P500. Moreover, we find that bitcoin is less volatile than commodities such as oil and silver, US Treasuries, AAA-rated corporate bonds, EU carbon credits, and some of the most popular technology and media stocks, including Apple, Twitter, and Netflix. Equally important, we find that during the March 2020 stock market crash triggered by COVID-19, the volatility of bitcoin was lower than that of most of these asset classes. The significant decline in bitcoin volatility over the past decade renders it more investable for conservative investors.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Thuy Anh Vo; Mieszko Mazur; An Thai
The impact of COVID-19 economic crisis on the speed of adjustment toward target leverage ratio: An international analysis Journal Article
In: Finance Research Letters, vol. 45, no. 45, pp. 102157, 2022.
@article{vo_4329,

title = {The impact of COVID-19 economic crisis on the speed of adjustment toward target leverage ratio: An international analysis},

author = {Thuy Anh Vo and Mieszko Mazur and An Thai},

url = {https://doi.org/10.1016/j.frl.2021.102157},

year  = {2022},

date = {2022-03-01},

journal = {Finance Research Letters},

volume = {45},

number = {45},

pages = {102157},

abstract = {This paper investigates changes in the speed of adjustment toward target leverage ratio under the impact of COVID-19 economic crisis. Using an international sample of publicly listed firms, we find that, on average, firms tend to adjust their capital structure more rapidly in the period following the breakout of COVID-19. Furthermore, we find that firms domiciled in countries in which COVID-19 causes more severe damage, adjust their target leverage quicker than firms domiciled in less severely affected countries. Overall, our study aims at developing a better understanding of the impact of COVID-19 on corporate financing decisions.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Man Dang; Premkanth Puwanenthiren; Hong An Thai; Mieszko Mazur; Edward Jones; Xuan Vinh Vo
Policy uncertainty and seasoned equity offerings methods Journal Article
In: International Review Of Financial Analysis, vol. 77, pp. 101830, 2021.
@article{dang_4330,

title = {Policy uncertainty and seasoned equity offerings methods},

author = {Man Dang and Premkanth Puwanenthiren and Hong An Thai and Mieszko Mazur and Edward Jones and Xuan Vinh Vo},

url = {https://doi.org/10.1016/j.irfa.2021.101830},

year  = {2021},

date = {2021-10-01},

journal = {International Review Of Financial Analysis},

volume = {77},

pages = {101830},

abstract = {Based on a sample of U.S. seasoned equity offering (SEO) during the period 2002-2017, we examine how the choice of equity issuance method changes in response to policy uncertainty. We find that firms subject to high policy uncertainty are less likely to use accelerated offerings rather than other types of traditional seasoned equity offerings. Our results are robust to alternative variable specifications, propensity score matching method, IV approach, and the inclusion of additional controls. Also, the effect of policy uncertainty on accelerated offering decision is weaker for firms with better information environment, earnings quality, and governance structures. Further, policy uncertainty increases the cost of funds and lowers long-run abnormal returns after SEOs for firms subject to high levels of policy uncertainty.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Man Dang; Ngoc Vu Nguyen; Mieszko Mazur; Premkanth Puwanenthiren; Ngoc Thang Nguyen
Global policy uncertainty and cross-border acquisitions Journal Article
In: Quarterly Review Of Economics And Finance, vol. 80, pp. 224-235, 2021.
@article{dang_4332,

title = {Global policy uncertainty and cross-border acquisitions},

author = {Man Dang and Ngoc Vu Nguyen and Mieszko Mazur and Premkanth Puwanenthiren and Ngoc Thang Nguyen},

url = {https://doi.org/10.1016/j.qref.2021.01.020},

year  = {2021},

date = {2021-05-01},

journal = {Quarterly Review Of Economics And Finance},

volume = {80},

pages = {224-235},

abstract = {Policy uncertainty has been documented to have a significant impact on corporate investment decisions. This paper investigates the effect of policy uncertainty on cross-border acquisitions. We find a significant monotonic relationship between the size of the acquired equity stake in a target firm and the level of policy uncertainty in the target's country of origin. More specifically, the acquirer is less inclined to purchase a sizeable ownership stake in the target firm, if the target is domiciled in unstable macroeconomic environment. Moreover, we find that acquirers are less willing to pay in cash if the target faces high policy uncertainty. The above results do not seem to depend on the quality of the country's institutional environment and are robust to alternative econometric specifications. Our study discusses policy implications and should be of interest to academics as well as finance practitioners.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Man Dang; Miguel Vega
COVID-19 and the march 2020 stock market crash. Evidence from S&P1500 Journal Article
In: Finance Research Letters, vol. 38, pp. 101690, 2021.
@article{mazur_4334,

title = {COVID-19 and the march 2020 stock market crash. Evidence from S&P1500},

author = {Mieszko Mazur and Man Dang and Miguel Vega},

url = {https://doi.org/10.1016/j.frl.2020.101690},

year  = {2021},

date = {2021-01-01},

journal = {Finance Research Letters},

volume = {38},

pages = {101690},

abstract = {This paper investigates the US stock market performance during the crash of March 2020 triggered by COVID-19. We find that natural gas, food, healthcare, and software stocks earn high positive returns, whereas equity values in petroleum, real estate, entertainment, and hospitality sectors fall dramatically. Moreover, loser stocks exhibit extreme asymmetric volatility that correlates negatively with stock returns. Firms react in a variety of different ways to the COVID-19 revenue shock. The analysis of the 8K and DEF14A filings of poorest performers reveals departures of senior executives, remuneration cuts, and (most surprisingly) newly approved cash bonuses and salary increases.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Salganik-Shoshan Galla
The effect of executive stock option delta and vega on the spin-off decision Journal Article
In: Quarterly Review Of Economics And Finance, vol. 72, no. 72, pp. 132-144, 2019.
@article{mazur_4331,

title = {The effect of executive stock option delta and vega on the spin-off decision},

author = {Mieszko Mazur and Salganik-Shoshan Galla},

url = {https://doi.org/10.1016/j.qref.2018.11.003},

year  = {2019},

date = {2019-05-01},

journal = {Quarterly Review Of Economics And Finance},

volume = {72},

number = {72},

pages = {132-144},

abstract = {We investigate the role of CEO incentives around asset restructuring known as corporate spin-off. More specifically, we focus on executive stock option delta and vega vis-à-vis changes in firm value and firm riskiness in response to the corporate spin-off. Controlling for self-selection of the spin-off decision, we find that executive stock option vega is positively related to changes in firm value as well as changes in firm risk. Conversely, we find that executive stock option delta is negatively related to changes in firm value and firm risk. Finally, we estimate the Fazzari et al. (1988) investment model and show that at the business segment level, CEO incentives are positively linked to capital spending. Overall, our study extends the current literature by documenting the role of executive stock option delta and vega in the context of corporate spin-offs.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Betty H.T. Wu; Mieszko Mazur
Managerial Incentives and Investment Policy in Family Firms: Evidence from a Structural Analysis: JOURNAL OF SMALL BUSINESS MANAGEMENT Journal Article
In: Journal Of Small Business Management, vol. 56, no. 4, pp. 618-657, 2018.
@article{wu_4335,

title = {Managerial Incentives and Investment Policy in Family Firms: Evidence from a Structural Analysis: JOURNAL OF SMALL BUSINESS MANAGEMENT},

author = {Betty H.T. Wu and Mieszko Mazur},

url = {https://doi.org/10.1111/jsbm.12308},

year  = {2018},

date = {2018-10-01},

journal = {Journal Of Small Business Management},

volume = {56},

number = {4},

pages = {618-657},

abstract = {This paper provides evidence that CEO incentive pay mediates the effect of family preferences on corporate investment policy. Our study focuses on the option portfolio volatility sensitivity vega, which motivates the risk-taking behavior of undiversified managers. After controlling for factors that affect incentive pay and investment policy simultaneously, we find that one-third of underinvestment in riskier R&D projects in active family firms can be attributed to a significantly lower vega. Passive family firms allocate more capital to R&D as opposed to active family firms, and are more active in M&A deal making. In contrast to many prior studies, pay incentives and families are not associated with capital expenditures. Overall, our empirical results suggest that CEO pay incentives induce investment policy contingent on firm risk. Family CEO incentive pay manifests the family preference for lower risk, especially in firms with higher firm risk. Nonetheless, after replacing family CEOs with outside professionals, investments in both R&D and M&A increase, which is consistent with the family preference for extended investment horizons. Interestingly, such a preference seems not to be manifested in incentive pay.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Galla Salganik-Shoshan; Thomas Walker; Jun Wang
Proximity and litigation: Evidence from the geographic location of institutional investors Journal Article
In: Journal Of Financial Markets, vol. 40, pp. 60-74, 2018.
@article{mazur_4336,

title = {Proximity and litigation: Evidence from the geographic location of institutional investors},

author = {Mieszko Mazur and Galla Salganik-Shoshan and Thomas Walker and Jun Wang},

url = {http://dx.doi.org/10.1016/j.finmar.2018.05.002},

year  = {2018},

date = {2018-09-01},

journal = {Journal Of Financial Markets},

volume = {40},

pages = {60-74},

abstract = {In this paper, we examine how the geographic distance between a firm and its largest institutional investors affects the firm's litigation risk. We show that geographic proximity between the firm and its largest institutional shareholders reduces the incidence of a lawsuit. Moreover, we find that geographic proximity affects the relationship between institutional investors' ownership and the litigation risk of their portfolio firms. These findings indicate that geographically proximate investors may have an informational advantage over investors who are located far away, and that this advantage manifests itself in more effective monitoring of firm management, and consequently, in lower litigation risk.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Galla Salganik-Shoshan; Maxim Elias
Comparing performance sensitivity of retail and institutional mutual funds' investment flows Journal Article
In: Finance Research Letters, vol. 22, pp. 66-73, 2017.
@article{mazur_4337,

title = {Comparing performance sensitivity of retail and institutional mutual funds' investment flows},

author = {Mieszko Mazur and Galla Salganik-Shoshan and Maxim Elias},

url = {https://doi.org/10.1016/j.frl.2016.12.031},

year  = {2017},

date = {2017-08-01},

journal = {Finance Research Letters},

volume = {22},

pages = {66-73},

abstract = {In this paper, we examine and compare the form of the flow-performance relationship for U.S. retail and institutional mutual funds. We provide evidence that the convex form of the flow-performance function documented by previous research characterizes mostly the relationship in the upper region of the performance scale. In contrast, the flow-performance relationship for the low-performance region appears to be concave. Furthermore, we document that the observed convexity is more pronounced for retail funds, while the concavity can be mainly attributed to institutional funds.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Betty H.T. Wu
Founding Family Firms, CEO Incentive Pay, and Dual Agency Problems: JOURNAL OF SMALL BUSINESS MANAGEMENT Journal Article
In: Journal Of Small Business Management, vol. 54, no. 4, pp. 1099-1125, 2016.
@article{mazur_4338,

title = {Founding Family Firms, CEO Incentive Pay, and Dual Agency Problems: JOURNAL OF SMALL BUSINESS MANAGEMENT},

author = {Mieszko Mazur and Betty H.T. Wu},

url = {https://doi.org/10.1111/jsbm.12237},

year  = {2016},

date = {2016-10-01},

journal = {Journal Of Small Business Management},

volume = {54},

number = {4},

pages = {1099-1125},

abstract = {This paper contributes to the literature on agency theory by examining relations between family involvement and CEO compensation. Using a panel of 362 small U.S. listed firms, we analyze how founding families influence firm performance through option portfolio price sensitivity. Consistent with the dual agency framework, we find that family firms have lower CEO incentive pay, which is further reduced by higher executive ownership. Interestingly, such incentive pay offsets the positive impact that families have on firm valuation. Collectively, our results show that, compared with nonfamily firms, lower incentive pay adopted by family firms due to lower agency costs mitigates the direct effect of family involvement on firm performance. Once accounting for CEO incentive pay, we do not observe performance differences between family and nonfamily firms.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur; Shage Zhang
Diversification discount over the long run: New perspectives Journal Article
In: Finance Research Letters, vol. 15, pp. 93-98, 2015.
@article{mazur_4339,

title = {Diversification discount over the long run: New perspectives},

author = {Mieszko Mazur and Shage Zhang},

url = {https://doi.org/10.1016/j.frl.2015.08.008},

year  = {2015},

date = {2015-11-01},

journal = {Finance Research Letters},

volume = {15},

pages = {93-98},

abstract = {We study the long-term trend of excess value and internal capital allocation of diversified firms from 1976 to 2013. The late 1970s and 1980s are characterized by large average diversification discount but narrow dispersion of excess value. Excess value of diversified firms becomes less negative on average after 1990, but its dispersion grows larger. In contrast, capital allocation efficiency of diversified firms converges significantly over time. Three quarters of diversified firms do not suffer from severe capital misallocation after the early 2000s. The effect of capital allocation efficiency on excess value varies over time and becomes larger in recent years.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mieszko Mazur
Creating M&A Opportunities through Corporate Spin?Offs Journal Article
In: Journal of Applied Corporate Finance, vol. 27, no. 3, pp. 137-143, 2015.
@article{mazur_4340,

title = {Creating M&A Opportunities through Corporate Spin?Offs},

author = {Mieszko Mazur},

url = {https://doi.org/10.1111/jacf.12137},

year  = {2015},

date = {2015-10-01},

journal = {Journal of Applied Corporate Finance},

volume = {27},

number = {3},

pages = {137-143},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
No posts by this author.
