



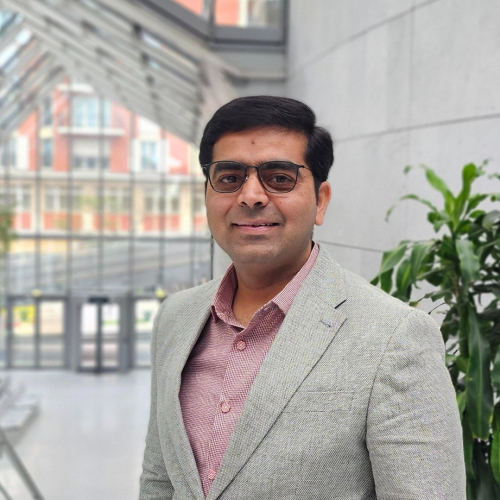
Ammar is an Associate Professor in the Department of Finance at EMLV Business School. Previously, he has held full-time academic position at ESSCA School of Management (France), Essex Business School (UK) and Ghulam Ishaq Khan Institute of Engineering Sciences and Technology (Pakistan). Ammar's research interests include corporate finance (executive compensation, risk management), corporate governance (board dynamics and diversity), corporate social responsibility performance and disclosure, financial reporting quality (earnings management and auditing). His research has appeared in leading international journals such as the British Journal of Management, Journal of Business Finance and Accounting, The British Accounting Review, and Journal of Business Ethics, among others. Ammar also serves on the editorial board of Journal of Applied Accounting Research and Journal of Financial Reporting and Accounting. He is an ad-hoc reviewer for several leading international journals such as The British Accounting Review, The International Journal of Accounting, Corporate Governance: An International Review, Journal of Business Ethics, and International Review of Financial Analysis, among others. He is a recipient of several internal and external research grants and supervises research students. Before joining academia, Ammar has worked in the banking sector for several years.


Yasir Shahab; Ammar Ali Gull; Muzhar Javed; Tanveer Ahsan
Do green firms select and terminate supply chain partners based on sustainability criteria? International evidence Journal Article
In: International Journal Of Production Economics, vol. 297, pp. 110000, 2026.
@article{shahab_4308,

title = {Do green firms select and terminate supply chain partners based on sustainability criteria? International evidence},

author = {Yasir Shahab and Ammar Ali Gull and Muzhar Javed and Tanveer Ahsan},

url = {https://doi.org/10.1016/j.ijpe.2026.110000},

year  = {2026},

date = {2026-07-01},

journal = {International Journal Of Production Economics},

volume = {297},

pages = {110000},

abstract = {The ?United Nations Global Compact? reiterates how important supply chain processes are for reaching sustainable growth targets. It points out that only eight supply chains contribute more than half of the world's greenhouse gas emissions. Thus, management of suppliers becomes crucial to meeting these goals. However, how green firms select and terminate their suppliers in response to mounting pressure of sustainability remains an area yet to be explored in operations management. To address these concerns, we investigate the data of listed firms from 38 countries over the 2002 to 2019 time-period. The results show that eco-friendly firms are more sensitive to sustainability practices of their suppliers while offering or terminating their contracts. Surprisingly, the stringency of environmental policy negatively moderates this relationship due to the substitution effect. Finally, we document that eco-innovative firms experience an increase in their market value when they select or terminate their supply chain partners based on sustainability criteria. The results offer vital theoretical and policy insinuations for the discipline of sustainable operations and supply chain management.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Usman Muhammad; Muhammad Khan; Ammar Ali Gull; Rizwan Mushtaq; Alaa Mansour Zalata
Female Board Directorships, the CEO-Employee Pay Ratio, and Firm Performance Journal Article
In: International Journal Of Finance & Economics, vol. 31, no. 3, pp. 4034-4056, 2026.
@article{muhammad_4111,

title = {Female Board Directorships, the CEO-Employee Pay Ratio,  and Firm Performance},

author = {Usman Muhammad and Muhammad Khan and Ammar Ali Gull and Rizwan Mushtaq and Alaa Mansour Zalata},

url = {https://doi.org/10.1002/ijfe.70133},

year  = {2026},

date = {2026-07-01},

journal = {International Journal Of Finance & Economics},

volume = {31},

number = {3},

pages = {4034-4056},

abstract = {Based on the premises of the social role theory, we investigate whether board gender composition may influence firm-level pay

inequality by improving the ability of boards to oversee managers and counter their influence on the compensation-setting process. Using the data of Chinese listed firms over the period 2007-2022, we investigate the relationship between female board

directorships, the CEO-employee pay ratio (pay inequality) and firm performance. Consistent with social role theory, we find

that firms with women directors on their boards have higher CEO-employee pay ratios, which have a positive impact on firm

performance. We find these results to be robust by using different measures of female board directorships, alternative sample

compositions and alternative estimation methods and by addressing any potential endogeneity concerns. Overall, our findings

support that women directors are effective in deciding the level of pay inequality that is linked to improved firm performance.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Nasir Ali; Falik Shear; Badar Nadeem Ashraf; Ammar Ali Gull; Zahid Hussain
Customer-Driven Corporate Environmental Initiatives and Shareholder Returns Journal Article
In: Business Strategy And The Environment, 2026.
@article{ali_4454,

title = {Customer-Driven Corporate Environmental Initiatives and Shareholder Returns},

author = {Nasir Ali and Falik Shear and Badar Nadeem Ashraf and Ammar Ali Gull and Zahid Hussain},

url = {https://doi.org/10.1002/bse.71128},

year  = {2026},

date = {2026-06-01},

journal = {Business Strategy And The Environment},

abstract = {As ESG considerations increasingly shape corporate and investor priorities, a central question remains: Do sustainability initiatives translate into shareholder returns? While ESG activities are often viewed as cost-inducing, stakeholder theory suggests they

can enhance financial performance by eliciting a positive response from stakeholders. This study tests that proposition by examining the impact of a customer-driven sustainability initiative, namely, eco-labeling, on corporate dividend policy. Our results

show that firms with eco-labeling certifications are more likely to pay dividends and exhibit higher dividend payout ratios, an

effect primarily driven by improved profitability. Further analysis reveals that eco-labeling certification has a positive impact on

the dividend policy of family firms. Taken together, these findings demonstrate that customer-led environmental initiatives not

only enhance operational performance but also lead to higher and more stable shareholder returns. The evidence highlights the

key role of market-driven sustainability demands in shaping dividend outcomes and shareholder returns in an emerging market.},

keywords = {},

pubstate = {online},

tppubtype = {article}

}
Mubashir Ali Khan; Ammar Ali Gull
CEO Power and Corporate Environmental Sustainability: An Examination of Waste Management Practices Journal Article
In: Business Strategy And The Environment, vol. 35, no. 4, pp. 4830-4845, 2026.
@article{khan_4060,

title = {CEO Power and Corporate Environmental Sustainability:  An Examination of Waste Management Practices},

author = {Mubashir Ali Khan and Ammar Ali Gull},

url = {https://doi.org/10.1002/bse.70414},

year  = {2026},

date = {2026-05-01},

journal = {Business Strategy And The Environment},

volume = {35},

number = {4},

pages = {4830-4845},

abstract = {This paper explores the influence of chief executive officer (CEO) power on corporate environmental sustainability through the lens of waste management, an underexplored yet critical aspect of environmental sustainability. Drawing on the approach-inhibition theory of power, we argue that powerful CEOs are more likely to engage in risk-taking behavior and exercise greater control over resources. Therefore, they may prioritize short-term profits over long-term sustainability. Using data from listed companies across 37 countries over the year 2002-2019, we find that high CEO power is positively linked with waste generation, implying that firms with powerful CEOs tend to produce more waste. Further analysis indicates that this relationship is stronger for firms in environmentally nonsensitive industries, in common-law countries, and with low governance quality. Our findings are robust to alternative estimations, cross-sectional analyses, variable measurements, and endogeneity tests. These results offer valuable insights into how CEO power shapes environmental sustainability, guiding regulators, stakeholders, and policymakers in assessing the impact of powerful CEOs on sustainability outcomes.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Muzhar Javed; Ammar Ali Gull; Abdul Ghafoor; Tanveer Ahsan; Muhammad Zahid Nawaz
Does Eco-Innovation Reinforce Better Waste Management? The Role of Industry Sensitivity and Environmental Policy Frameworks Journal Article
In: Business Strategy And The Environment, vol. 35, no. 4, pp. 5285-5307, 2026.
@article{javed_4062,

title = {Does Eco-Innovation Reinforce Better Waste Management?  The Role of Industry Sensitivity and Environmental  Policy Frameworks},

author = {Muzhar Javed and Ammar Ali Gull and Abdul Ghafoor and Tanveer Ahsan and Muhammad Zahid Nawaz},

url = {https://doi.org/10.1002/bse.70426},

year  = {2026},

date = {2026-05-01},

journal = {Business Strategy And The Environment},

volume = {35},

number = {4},

pages = {5285-5307},

abstract = {Environmental sustainability is a critical global concern, and waste generation poses a major threat to ecological balance. We investigate eco-innovation's role in enhancing waste management practices via the natural-resource-based view and dynamic capability perspective. While eco-innovation is recognized as a key strategy for sustainability, empirical evidence on its direct impact on firm-level waste management performance remains limited, creating a critical research gap. Using a dataset of publicly listed firms from 42 countries, covering 17,339 firm-year observations from 2002 to 2019, we find a positive and significant relationship between eco-innovation and waste management performance. This relationship is especially pronounced in environmentally sensitive industries, firms with formal waste reduction policies, and countries with stringent environmental regulations. By integrating two strategic management frameworks, this study deepens theoretical understanding while extending empirical evidence across a broad geographical and temporal scope. Our study thus addresses a key literature gap by providing large-scale, cross-country evidence that positions eco-innovation as a dynamic capability directly relevant to waste management. Our findings highlight the value of eco-innovation as a dynamic capability that supports firms in more effectively addressing environmental challenges. There are key implications for managers, policymakers, and scholars, given eco-innovation's key role in supporting sustainable development and several United Nations Sustainable Development Goals.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Abdul Ghafoor; Yasar Bayraktar; Ammar Ali Gull; Mirzet ?eho
Executive compensation clawbacks and corporate climate engagement Journal Article
In: Journal of Accounting Literature, pp. 1-28, 2026.
@article{ghafoor_4309,

title = {Executive compensation clawbacks and corporate climate engagement},

author = {Abdul Ghafoor and Yasar Bayraktar and Ammar Ali Gull and Mirzet ?eho},

url = {https://doi.org/10.1108/JAL-02-2025-0053},

year  = {2026},

date = {2026-03-01},

journal = {Journal of Accounting Literature},

pages = {1-28},

abstract = {Purpose


The purpose of this study is to investigate how the adoption of executive compensation clawbacks affects the climate engagement initiatives of firms listed in the US Based on agency theory, we test two competing arguments - (1) the proactive risk management view and (2) the excessive caution view - to examine whether clawback provisions improve or constrain corporate climate engagement efforts.

Design/methodology/approach


Our sample includes firms listed in the US from 1996 to 2017. We measure corporate climate engagement by creating a Climate Engagement Index (CINDEX) based on four variables: (1) the appointment of sustainability executives, (2) Carbon Disclosure Project reporting, (3) climate-related lobbying and (4) pro-climate coalition membership. To investigate causality and mitigate possible endogeneity issues, we employ several empirical methods, including propensity score matching, instrumental variable regression and a battery of robustness tests.

Findings


Our results support the proactive risk management view. We find that clawback provisions increase corporate climate engagement. Specifically, firms adopting clawback provisions exhibit an increase in climate engagement of approximately 0.12 standard deviations relative to firms without such provisions. Furthermore, we show that the positive effect of clawback provisions persists across both environmentally sensitive and non-sensitive industries, as well as in firms with or without ESG-linked compensation policies. Finally, we document that climate engagement initiatives driven by clawback provisions reduce firms' exposure to climate change risks.

Practical implications


Our results have practical implications, showing that clawback provisions are valuable governance tools that promote corporate climate engagement and help mitigate climate-related risks. Boards, managers and investors should consider clawbacks not only as safeguards against misconduct but also as mechanisms to align executive incentives with environmental objectives. Policymakers and regulators have a clear role in incorporating clawback provisions into sustainability frameworks to strengthen corporate accountability and support long-term climate goals.

Originality/value


Our study extends the existing literature on clawback provisions beyond financial outcomes by linking them to corporate sustainability. We identify clawback provisions as a key governance mechanism for promoting climate engagement and demonstrate their effectiveness across various organizational contexts. This contributes to a deeper understanding of how compensation-based governance mechanisms affect environmental performance.},

keywords = {},

pubstate = {online},

tppubtype = {article}

}
Radwan Alkebsee; Ammar Ali Gull; Asad Ali Rind
Tax avoidance and CEO turnover: evidence from China Journal Article
In: China Journal of Accounting Research, vol. 19, no. 1, pp. 100457, 2026.
@article{alkebsee_4068,

title = {Tax avoidance and CEO turnover: evidence from China},

author = {Radwan Alkebsee and Ammar Ali Gull and Asad Ali Rind},

url = {https://doi.org/10.1016/j.cjar.2025.100457},

year  = {2026},

date = {2026-03-01},

journal = {China Journal of Accounting Research},

volume = {19},

number = {1},

pages = {100457},

abstract = {As the literature documents inconclusive evidence on whether tax avoidance affects CEO turnover, we examine the impact of tax avoidance on forced CEO turnover and the moderating effect of ownership structure, political connections and regional tax enforcement on this relationship. Using data on Chinese listed firms involving 10,653 observations for the 2011-2018 period, we test our hypotheses using logistic regressions. We find that tax avoidance is positively associated with forced CEO turnover, suggesting that tax-avoiding firms are more likely to face leadership crises. Furthermore, the positive association is pronounced for firms that are state-owned, lack political connections or are located in developed regions with active tax enforcement. Our results, which are robust to alternative proxies and endogeneity tests, should interest policymakers and investors as they demonstrate the impact of tax avoidance on corporate governance and leadership.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Usman Muhammad; Alaa Mansour Zalata; Ammar Ali Gull; Nanyan Dong
Alleviating Related Party Transactions Through Corporate Social Responsibility Journal Article
In: International Journal Of Finance & Economics, 2026.
@article{muhammad_4258,

title = {Alleviating Related Party Transactions Through Corporate Social Responsibility},

author = {Usman Muhammad and Alaa Mansour Zalata and Ammar Ali Gull and Nanyan Dong},

url = {https://doi.org/10.1002/ijfe.70177},

year  = {2026},

date = {2026-03-01},

journal = {International Journal Of Finance & Economics},

abstract = {Using a sample of Chinese firms from 2010 to 2021, we examine whether corporate social responsibility (CSR) influences firms' propensity to engage in related-party transactions (RPTs)?an intriguing yet underexplored relationship. We find robust evidence that CSR-oriented firms are less likely to permit RPTs. Our results further indicate that RPTs conducted by more CSR-oriented firms are viewed favourably by the market and are associated with higher subsequent market value. In contrast, RPTs among other firms correlate with reduced market value, suggesting that CSR-oriented firms only allow efficient RPTs to meet legitimate needs and align with strategic value-maximisation objectives. Additional analysis reveals that ownership structure and firm-level governance quality moderate the CSR-RPTs relationship. These findings remain robust to alternative RPT measures and are not driven by endogeneity concerns.},

keywords = {},

pubstate = {online},

tppubtype = {article}

}
Radwan Alkebsee; Ammar Ali Gull; Abdul Ghafoor
The Governance Role of Independent Directors' Cash Compensation in Suspect Firms? Evidence From Real Earnings Management Journal Article
In: International Journal Of Finance & Economics, vol. 31, no. 1, pp. 241-269, 2026.
@article{alkebsee_3596,

title = {The Governance Role of Independent Directors' Cash  Compensation in Suspect Firms? Evidence From Real  Earnings Management},

author = {Radwan Alkebsee and Ammar Ali Gull and Abdul Ghafoor},

url = {https://doi.org/10.1002/ijfe.3137},

year  = {2026},

date = {2026-01-01},

journal = {International Journal Of Finance & Economics},

volume = {31},

number = {1},

pages = {241-269},

abstract = {This study examines the relationship between independent directors' cash compensation and real earnings management. Using the data of Chinese suspect firms over the period 2009-2023, we show that independent directors' cash compensation helps suspect firms reduce the magnitude of real earnings management, suggesting that cash-based compensation to independent directors enhances board independence and the effectiveness of its monitoring role over real earnings management. Further analysis shows that this relationship is significantly influenced by the ownership structure. Specifically, we find that non-state and foreign ownership strengthen the negative association between independent directors' cash compensation and real earnings management, implying that these investors enhance the governance role of independent directors' cash compensation in monitoring the opportunistic behaviour of managers. Our main findings are robust to alternate proxies of earnings management, sample composition, and endogeneity concerns using several econometric techniques. The study contributes to the related literature by providing empirical evidence on the association between non-equity compensation for independent directors and real earnings management in suspect firms. Our study also offers significant implications for international investors, firms, and regulators, especially after the inclusion of Chinese stocks in the MSCI indices.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Muhammad Usman; Muhammad Khan; Ammar Ali Gull; Rizwan Mushtaq; Alaa Mansour Zalata
Female Board Directorships, the CEO-Employee Pay Ratio, and Firm Performance Journal Article
In: International Journal Of Finance & Economics, 2026.
@article{usman_4111,

title = {Female Board Directorships, the CEO-Employee Pay Ratio,  and Firm Performance},

author = {Muhammad Usman and Muhammad Khan and Ammar Ali Gull and Rizwan Mushtaq and Alaa Mansour Zalata},

url = {https://doi.org/10.1002/ijfe.70133},

year  = {2026},

date = {2026-01-01},

journal = {International Journal Of Finance & Economics},

abstract = {Based on the premises of the social role theory, we investigate whether board gender composition may influence firm-level pay

inequality by improving the ability of boards to oversee managers and counter their influence on the compensation-setting process. Using the data of Chinese listed firms over the period 2007-2022, we investigate the relationship between female board

directorships, the CEO-employee pay ratio (pay inequality) and firm performance. Consistent with social role theory, we find

that firms with women directors on their boards have higher CEO-employee pay ratios, which have a positive impact on firm

performance. We find these results to be robust by using different measures of female board directorships, alternative sample

compositions and alternative estimation methods and by addressing any potential endogeneity concerns. Overall, our findings

support that women directors are effective in deciding the level of pay inequality that is linked to improved firm performance.},

keywords = {},

pubstate = {online},

tppubtype = {article}

}
Ammar Ali Gull; Muhammad Atif; Asad Ali Rind
Do Women Directors Drive Firm's Climate Risk Disclosure? An International Evidence Journal Article
In: Business Strategy And The Environment, vol. 35, no. 1, pp. 57-83, 2026.
@article{gull_4058,

title = {Do Women Directors Drive Firm's Climate Risk Disclosure?  An International Evidence},

author = {Ammar Ali Gull and Muhammad Atif and Asad Ali Rind},

url = {https://doi.org/10.1002/bse.70165},

year  = {2026},

date = {2026-01-01},

journal = {Business Strategy And The Environment},

volume = {35},

number = {1},

pages = {57-83},

abstract = {The paper examines the role of women directors in climate risk disclosure using a comprehensive measure in an international setting. Grounded in stakeholder orientation, resource dependence, and legitimacy theories, the paper analyzes 26,289 firm-year observations across 42 countries from 2002 to 2019 and documents that a higher proportion of women directors enhances climate risk disclosure, particularly women independent directors. Additionally, global gender quota reforms strengthen this relationship, and women directors and climate risk disclosure collectively contribute to improving firm performance. These results hold various robustness tests, including endogeneity assessments. This research contributes to the ongoing discourse on the business case for board gender diversity and provides valuable insights for regulators, investors, and policymakers.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Aitzaz Ahsan Alias Sarang; Irfan Haider Shakri; Asad Ali Rind
ESG-based executive compensation and waste management: Global evidence Journal Article
In: Journal Of Environmental Management, vol. 394, pp. 127367, 2025.
@article{gull_4059,

title = {ESG-based executive compensation and waste management:  Global evidence},

author = {Ammar Ali Gull and Aitzaz Ahsan Alias Sarang and Irfan Haider Shakri and Asad Ali Rind},

url = {https://doi.org/10.1016/j.jenvman.2025.127367},

year  = {2025},

date = {2025-11-01},

journal = {Journal Of Environmental Management},

volume = {394},

pages = {127367},

abstract = {The world generates over 2 billion tons of solid waste annually, which is estimated to rise by 70 % by 2050 due to population growth, urbanization, and industrialization. This escalating waste crisis severely threatens human habitats, endangering both environmental and public health. Effective waste management becomes critical in combating global warming as solid waste generation rises. In this vein, the current study investigates the impact of executives' environmental, social, and governance (ESG) compensation on waste management practices within firms worldwide. We utilize a dataset spanning 43 countries and comprising 17,443 firm-year observations from 2002 to 2019. We employ the system generalized method of moments (GMM) to analyze the relationship between executives' ESG compensation and waste management. Our findings reveal that executives' compensation tied to ESG performance is associated with reduced waste generation and increased recycling initiatives. Specifically, an increase of one standard deviation in ESG compensation reduces total waste by 1.07 %. We also observe a similar association between ESG compensation policy and waste management. However, the relationship between executives' ESG compensation and waste management is more pronounced for firms operating in environmentally sensitive and low-stringency environments than those operating in environmentally non-sensitive industries and under high-stringency conditions. Additionally, we find that this relationship is pronounced for firms with low levels of firm-level corporate governance quality compared to those with high levels. This research informs policymakers and stakeholders by highlighting the importance of incorporating ESG considerations into executive compensation contracts to promote sustainable waste management practices and preserve the environment.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Asad Ali Rind; Muhamamd Tahir Suleman
Do Co-Opted Boards Lead to Managerial Obfuscation? Evidence From the 10-K Report Readability Journal Article
In: International Journal Of Finance & Economics, vol. 30, no. 4, pp. 4151-4181, 2025.
@article{gull_3296,

title = {Do Co-Opted Boards Lead to Managerial Obfuscation?  Evidence From the 10-K Report Readability},

author = {Ammar Ali Gull and Asad Ali Rind and Muhamamd Tahir Suleman},

url = {https://doi.org/10.1002/ijfe.3114},

year  = {2025},

date = {2025-10-01},

journal = {International Journal Of Finance & Economics},

volume = {30},

number = {4},

pages = {4151-4181},

abstract = {This paper examines the relationship between board co-option and managerial obfuscation captured through linguistic complexity of 10-K reports. Using 7912 US firm-year observations from 2003 to 2018, we find that firms with a higher proportion of

co-opted directors obfuscate the readability of the 10-K reports. The findings are robust across various variable definitions, sample specifications and remain significant after addressing endogeneity concerns through multiple approaches, including leadlag regression, entropy balancing, instrumental variable analysis, the system GMM, and difference-in-difference estimations.

Further analysis reveals that our main finding is driven by firms with weak internal (i.e., those with high CEO power and low

board meeting attendance) and external (i.e., those with low institutional ownership and less analyst following) monitoring. The

paper provides useful policy insights and implications for investors, regulators, and policymakers},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Rizwan Ali; Tanveer Ahsan; Ramiz ur Rehman
Institutional ownership and waste management: international evidence Journal Article
In: Journal of Accounting Literature, pp. 1-29, 2025.
@article{gull_4061,

title = {Institutional ownership and waste  management: international evidence},

author = {Ammar Ali Gull and Rizwan Ali and Tanveer Ahsan and Ramiz ur Rehman},

url = {https://doi.org/10.1108/JAL-11-2024-0335},

year  = {2025},

date = {2025-10-01},

journal = {Journal of Accounting Literature},

pages = {1-29},

abstract = {Purpose - The ethical framework of social responsibility requires individuals and businesses to ensure

sustainable consumption and production patterns. Corporations responsible for a significant proportion of

global waste are compelled to better manage their waste. Given that institutional ownership is a key pillar

of corporate governance, we aim to investigate its impact on waste production and recycling.

Design/methodology/approach - We collected an international dataset of firms listed in 42 countries between

2002 and 2019, comprising 17,272 firm-year observations. We applied panel data regression techniques to

investigate the impact of institutional ownership on corporate waste management while accounting for time,

industry and country-fixed effects and endogeneity issues due to reverse causality (2SLS and GMM) and

selection bias (PSM).

Findings - Our findings reveal that institutional ownership leads to reduced waste production and increased

recycling. Particularly, when institutional ownership increases by one standard deviation, waste generation

(recycling) decreases (rises) by 1.008 tons (0.64%). These findings are robust to alternative proxies, various

econometric techniques and robustness analyses. Our cross-sectional analyses show that when institutional

investors are present, there is better waste management in firms with low governance quality, low environmental

orientation, firms operating in developed (i.e. G10) countries and firms having waste governance mechanisms.

Taken together, our results demonstrate the socially responsible and ethical role of institutional investors toward

environmental issues.

Research limitations/implications - The data, sourced from ASSET4 and WorldScope, primarily covers large

firms, which may restrict the generalizability of our findings to small and medium-sized enterprises. Variations in

governance structures and regulatory environments across countries may also influence corporate waste

management practices, requiring cautious interpretation of the results in different national contexts. Additionally,

due to data constraints, we were unable to distinguish between controllable and uncontrollable waste.

Practical implications - Our results suggest that institutional investors help reduce corporate waste and

enhance recycling; therefore, the policymakers of global institutions may include institutional investors in their

strategies to tackle waste and ensure sustainable production.

Originality/value - To the best of the authors' knowledge, this is the first study that investigates the impact of

institutional ownership on corporate waste management using an international dataset. Aligned with agency

theory, our findings indicate that institutional ownership enhances corporate governance efficiency by

facilitating extra monitoring and decreasing information asymmetry. Consequently, enhanced corporate

governance mechanisms play a key role in better waste management.},

keywords = {},

pubstate = {online},

tppubtype = {article}

}
Ammar Ali Gull; Inam Ul Haq; Abdul Ghafoor; Tanveer Ahsan; Yasar Bayraktar
When do female directors curb corporate ESG controversies? Evidence from the USA Journal Article
In: Journal Of Cleaner Production, vol. 528, pp. 146746, 2025.
@article{gull_3930,

title = {When do female directors curb corporate ESG controversies? Evidence from the USA},

author = {Ammar Ali Gull and Inam Ul Haq and Abdul Ghafoor and Tanveer Ahsan and Yasar Bayraktar},

url = {https://doi.org/10.1016/j.jclepro.2025.146746},

year  = {2025},

date = {2025-10-01},

journal = {Journal Of Cleaner Production},

volume = {528},

pages = {146746},

abstract = {Global concerns regarding sustainability and gender equality prompt corporations to restructure their operations. In response to the stakeholders' pressure, they have increasingly started prioritizing the United Nations' Sustainable Development Goals (SDGs). This shift towards sustainability pushes them to pursue stakeholders' legitimacy. Consequently, corporations have initiated appointing more female directors to boards to mitigate ESG controversies. The literature reveals that board gender diversity improves corporate sustainability performance. However, there is still a need to clarify when female directors have the most positive effect on corporate behavior. To this end, we aim to investigate when specifically female directors curb corporate ESG controversies. Interestingly, we find that they mitigate ESG controversies when acting as independent directors, not executive ones. Additionally, their impact in curbing ESG controversies is significant in firms with sustainability-linked compensation policies, weak governance mechanisms, and those that belong to environmentally sensitive industries. The mechanism analysis reveals that female independent directors mitigate ESG controversies by enhancing transparency through their effective monitoring. The results of our study are robust to endogeneity regarding reverse causality, industry, and time-fixed effects. Our results offer several contributions to the governance and sustainability literature by documenting the significant role of female directors in addressing sustainability issues.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Umer Iqbal; Abdul Ghafoor; Ammad Ahmed
Navigating the black box: board co-option and environmental innovation Journal Article
In: Journal of Accounting Literature, 2025.
@article{gull_3435,

title = {Navigating the black box: board co-option and environmental innovation},

author = {Ammar Ali Gull and Umer Iqbal and Abdul Ghafoor and Ammad Ahmed},

url = {https://doi.org/10.1108/JAL-05-2024-0103},

year  = {2025},

date = {2025-03-01},

journal = {Journal of Accounting Literature},

abstract = {Purpose

This study examines the impact of board co-option on environmental innovation and the moderating effect of firms' industrial context, ESG compensation and environmental policy stringency (EPS) on this relationship. Finally, we examine the implications of the board co-option and eco-innovation nexus on the market value of firms.


Design/methodology/approach

This study employs the system generalized method of moments (GMM) estimator on a longitudinal panel dataset of the US-listed firms to test the proposed hypotheses. The system GMM findings are substantiated using the entropy balancing method and difference-in-differences (DiD) estimations to better establish causality while addressing endogeneity concerns.


Findings

The findings provide evidence that board co-option has a negatively significant relationship with environmental innovation. Further analyses imply that the impact of board co-option on environmental innovation is positively significant among firms operating in environmentally sensitive industries, with ESG compensation for executives, and those operating in environments characterized by high environmental policy stringency. Taken together, these results suggest that industrial context, ESG compensation and environmental policy stringency moderate the impact of board co-option on environmental innovation. The results also reveal that more environmentally innovative firms attain greater market valuation when the board is co-opted.


Originality/value

This study is a novel attempt to contribute to the debate on board composition and its impact on corporate environmental innovation. It complements the existing literature on sustainability governance and accounting by providing an understanding of the impact of board co-option on corporate environmental innovation and highlights the role of regulatory pressure, industrial context and executive compensation structure in shaping this relationship. The findings offer valuable insights for academics, senior management and policymakers.},

keywords = {},

pubstate = {online},

tppubtype = {article}

}
Usman Muhammad; Maria Ishaque; Ammar Ali Gull; Vincent Tawiah
Partial privatisation and green innovation in China: The role of industrial context and regional development Journal Article
In: Business Strategy And The Environment, vol. 33, no. 7, pp. 6814-6832, 2024.
@article{muhammad_3051,

title = {Partial privatisation and green innovation in China: The role of industrial context and regional development},

author = {Usman Muhammad and Maria Ishaque and Ammar Ali Gull and Vincent Tawiah},

url = {https://onlinelibrary.wiley.com/doi/10.1002/bse.3834},

year  = {2024},

date = {2024-11-01},

journal = {Business Strategy And The Environment},

volume = {33},

number = {7},

pages = {6814-6832},

abstract = {This study examines the relationship between partial privatisation (i.e., state ownership reduction) and green innovation in China. Employing a large dataset of 36,072?firm-year observations between 2005 and 2022, we document a positively significant association between partial privatisation and green innovation, suggesting that privatisation promotes green innovation in Chinese firms. Further analyses shows that the relationship is stronger for firms in environmentally sensitive industries and those located in more developed regions. Our main finding is robust to the alternative measurement of variables and endogeneity concerns using the propensity score matching (PSM), firm-fixed effects and the system generalised method of moments (GMM) approach. Finally, we document that green innovation in privatised firms yields superior performance. Our findings highlight the significant contribution of privatisation in the quest for low-carbon emissions in China by promoting green innovation.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Ammar Abid; Asad Ali Rind; Dildar Hussain
Women directors and CSR report assurance: An international examination Journal Article
In: Comptabilite Controle Audit, vol. 30, no. 3, 2024.
@article{gull_3260,

title = {Women directors and CSR report assurance: An international examination},

author = {Ammar Ali Gull and Ammar Abid and Asad Ali Rind and Dildar Hussain},

url = {https://doi.org/10.3917/cca.303.0001},

year  = {2024},

date = {2024-10-01},

journal = {Comptabilite Controle Audit},

volume = {30},

number = {3},

abstract = {This paper examines whether women directors impact the firm's likelihood of seeking corporate social responsibility (CSR) report assurance. Using a global dataset for the period 2002-2019, we find robust results that women directors drive the firm's likelihood of seeking CSR report assurance from external auditors. The results also reveal that women directors impact CSR report assurance when they are in a critical mass. Furthermore, both executive and non-executive women directors impact the firm's likelihood of seeking CSR report assurance; however, the relationship is more pronounced for executive women directors. We also show that the relationship of women directors with CSR report assurance is only significant for firms operating in environmentally sensitive industries. The cross-sectional analysis also exhibits that our main finding holds only for firms with weak governance and low CSR orientation. Finally, we document that the CSR committee channels the impact of women directors on the firm's likelihood of seeking CSR report assurance. The results provide interesting insights into the governance-CSR assurance nexus and have important practical implications for stakeholders globally.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Hoa Luong; Muhammad Nadeem
Board co-option and corporate environmental orientation: New insights from the waste management perspective Journal Article
In: Corporate Governance-An International Review, vol. 32, no. 5, pp. 758-785, 2024.
@article{gull_2682,

title = {Board co-option and corporate environmental orientation: New insights from the waste management perspective},

author = {Ammar Ali Gull and Hoa Luong and Muhammad Nadeem},

url = {https://doi.org/10.1111/corg.12567},

year  = {2024},

date = {2024-09-01},

journal = {Corporate Governance-An International Review},

volume = {32},

number = {5},

pages = {758-785},

abstract = {Research Question/Issue

We investigate the impact of board co-option on corporate environmental orientation from the perspective of waste management. As waste presents damaging effects on the natural environment, climate change, and human health, businesses assume an ethical responsibility to conduct their operations in a sustainable and responsible manner.


Research Findings/Insights

Employing firm-level waste production data, we document a significant negative relationship between board co-option and waste generation, suggesting that co-opted directors help firms reduce their waste?a finding that also carries economic significance. The cross-sectional analyses reveal that the relationship only holds when a CEO does not chair the board and has a shorter tenure. Furthermore, we find that the board co-option-waste management relationship is stronger in environmentally sensitive industries and is mainly driven by the manufacturing firms. We perform a battery of analyses to rule out endogeneity concerns and check for the robustness of our results. The channel test reveals that CEOs of firms with higher waste management face lower performance-induced turnover, particularly when working with co-opted boards. Finally, we also find that co-option-induced waste management initiatives ultimately increase firms' economic value.


Theoretical/Academic Implications

We document that co-opted boards may enhance firms' waste management practices by reducing performance-induced CEO turnover. Thus, we make important contributions to the corporate governance and environmentalism strands of the literature by highlighting the bright side of board co-option for waste reduction initiatives.


Practitioner/Policy Implications

Our study provides vital policy implications for regulators and top management teams against the background of public outcry and social pressure to mitigate the damage to the environment and calls for ethical business practices.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Asif Saeed; Noor Zahid; Rizwan Mushtaq; Ammar Ali Gull
Moving towards sustainable waste management: a critical analysis of corporate governance Journal Article
In: International Journal of Business Governance and Ethics, vol. 48, no. 4-5, pp. 554-58, 2024.
@article{saeed_4398,

title = {Moving towards sustainable waste management: a critical analysis of corporate governance},

author = {Asif Saeed and Noor Zahid and Rizwan Mushtaq and Ammar Ali Gull},

url = {https://doi.org/10.1504/IJBGE.2024.139641},

year  = {2024},

date = {2024-07-01},

journal = {International Journal of Business Governance and Ethics},

volume = {48},

number = {4-5},

pages = {554-58},

abstract = {An increase in the level of greenhouse gases concentration has drawn global attention towards the preservation of the natural ecosystem. In response to stakeholders' pressure, firms are adopting sustainable business practices for reducing their impact on the environment. Among these, firms monitor their waste management practices to reduce the ecological rucksack in their production cycles. We therefore explore the relationship between corporate governance and waste management practices. Based on a panel data set of listed firms from 33 countries during 2002-2017, the results indicate that high corporate governance quality is positively associated with effective waste management practices. Our results remain robust to alternate proxies of waste management and endogeneity concerns. Moreover, the relationship between corporate governance and waste management is eminent in firms with institutional investors, BIG4 auditors, highly intense R&D structure and during the non-crisis period. We interpret our results using stakeholder theory and triple bottom line theory and provide necessary implications.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ansar Majeed; Tanveer Ahsan; Ammar Ali Gull
Does corruption sand the wheels of sustainable development? Evidence through green innovation Journal Article
In: Business Strategy And The Environment, vol. 33, no. 5, pp. 4626-4651, 2024.
@article{majeed_2859,

title = {Does corruption sand the wheels of sustainable development? Evidence through green innovation},

author = {Ansar Majeed and Tanveer Ahsan and Ammar Ali Gull},

url = {https://doi.org/10.1002/bse.3719},

year  = {2024},

date = {2024-07-01},

journal = {Business Strategy And The Environment},

volume = {33},

number = {5},

pages = {4626-4651},

abstract = {This study investigates the impact of corruption on green innovation, as corruption

may impede or foster green innovation in developing economies due to their weak

governance systems. We develop a dataset of Chinese non-financial firms listed

between 2007 and 2020 and apply static and dynamic regression techniques. The

results indicate a highly significant negative association between corruption and

green innovation. This supports the notion that corruption culture reduces corporate

legitimacy concerns (institutional theory), increases managerial rent-seeking (agency

theory), and hinders green innovation, thus impeding sustainable development and

supporting the ?sand the wheels? hypothesis. Our analysis also reveals that corruption's negative impact on green innovation is particularly significant for firms with

lower media and analyst coverage, non-state-owned firms, and firms in heavypolluting industries. These results are robust to alternate proxies of green innovation

and corruption as well as econometric specifications that account for endogeneity

issues and industry, region, and time-fixed effects.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Mariela Carvajal; Muhammad Atif; Muhammad Nadeem
The presence and composition of sustainability committee and waste management practices Journal Article
In: International Review Of Financial Analysis, vol. 93, pp. 103111, 2024.
@article{gull_2792,

title = {The presence and composition of sustainability committee and waste management practices},

author = {Ammar Ali Gull and Mariela Carvajal and Muhammad Atif and Muhammad Nadeem},

url = {ttps://doi.org/10.1016/j.irfa.2024.103111},

year  = {2024},

date = {2024-05-01},

journal = {International Review Of Financial Analysis},

volume = {93},

pages = {103111},

abstract = {Motivated by the recent surge in scholarly enquiries into the role of sustainability committees in corporate social responsibility, this study investigates the relevance of sustainability committees' presence and composition to waste management practices, which is still unknown in the literature. Based on a panel of firms listed in 42 countries from 2002 to 2019, we document a positively significant (insignificant) relationship between the presence of a sustainability committee and waste generation (waste recycling). In terms of the composition, we find that firms with large committee size and gender diversity (committee tenure and independence) generate less (more) waste. Our analysis also indicates that firms with gender-diverse committees are more likely to recycle their waste. Our findings are robust to alternative estimation techniques and variable specifications, sub-sample analyses, and different identification strategies. This study provides new insights into the structure of the sustainability committee and informs stakeholders and regulators about impression management by firms across countries.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Muhammad Atif; Usman Muhammad
Informal Institutions and Audit Pricing: Cross-Country Evidence of National Culture and Audit Fees Journal Article
In: International Journal of Accounting, vol. 52, no. 2, pp. 2450008, 2024.
@article{gull_2967,

title = {Informal Institutions and Audit Pricing: Cross-Country Evidence of National Culture and Audit Fees},

author = {Ammar Ali Gull and Muhammad Atif and Usman Muhammad},

url = {https://www.worldscientific.com/doi/full/10.1142/S1094406024500082},

year  = {2024},

date = {2024-05-01},

journal = {International Journal of Accounting},

volume = {52},

number = {2},

pages = {2450008},

abstract = {The research problem


In this study, we examined the effect of an important informal institution, namely, national culture, on audit fees in an international context.


Motivation


In recent years, extant literature has increasingly focused on country-level differences in the audit environment, as these might have a significant influence on how financial statement audits are conducted across the globe. We contribute to this stream of literature by investigating the impact of national culture on audit fees.


The test hypotheses


Based on the demand- and supply-side perspectives of audit fees, we hypothesized that national culture dimensions ? namely, uncertainty avoidance, power distance, individualism versus collectivism, and masculinity versus femininity ? affect audit fees.


Target population


We used a sample of 27,670 firm-year observations across 22 countries over the 2002-2019 period.


Adopted methodology


We used ordinary least squares (OLS) regressions as baseline technique and entropy-balanced method (EBM) and system-generalized method of moments (GMM) to address endogeneity concerns.


Analyses


We examined the impact of Hofstede's four national culture dimensions ? uncertainty avoidance, power distance, individualism versus collectivism, and masculinity versus femininity ? on audit fees. We also tested the robustness of results using alternative measures of national culture, subsample analyses, and additional firm-level factors.


Findings


Consistent with our hypotheses, we find that audit fees are higher (lower) in countries with higher uncertainty avoidance, individualism, and masculinity (power distance) scores. Our further analyses reveal that earnings management proxied by abnormal accruals does not impact the relationship; however, country-level creditor rights influence audit fees in high power distance and masculine cultures. We also note that national culture influences auditor choice and audit opinion. Our main findings are robust to alternate proxies and subsample analysis, as well as to address potential endogeneity concerns. Overall, our findings offer important implications for firms operating in global markets and for the audit profession.},

note = {The paper has not been assigned to any issue yet.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Abdul Ghafoor; Ammar Ali Gull
Do co-opted boards protect CEOs from ESG controversies? Journal Article
In: Finance Research Letters, vol. 63, pp. 105263, 2024.
@article{ghafoor_2904,

title = {Do co-opted boards protect CEOs from ESG controversies?},

author = {Abdul Ghafoor and Ammar Ali Gull},

url = {https://www.sciencedirect.com/science/article/abs/pii/S1544612324002939},

year  = {2024},

date = {2024-05-01},

journal = {Finance Research Letters},

volume = {63},

pages = {105263},

abstract = {We investigate the relationship between board co-option and ESG controversies using a large sample of U.S. firms from 2002 to 2018. Contrary to prior studies documenting the potential consequences of co-opted boards on organizational outcomes, we document the positive role of co-opted directors. Specifically, the CEOs of firms with a higher proportion of co-opted directors are subject to fewer ESG controversies. Our findings provide significant implications for stakeholders, redirecting the narrative on board co-option.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Nazim Hussain; Sanna Akbar Khan; Zaheer Khan; Asif Saeed
Governing corporate social responsibility decoupling: The effect of the governance committee on corporate social responsibility decoupling Journal Article
In: Journal Of Business Ethics, vol. 185, pp. 349-374, 2023.
@article{gull_2632,

title = {Governing corporate social responsibility decoupling: The effect of the governance committee on corporate social responsibility decoupling},

author = {Ammar Ali Gull and Nazim Hussain and Sanna Akbar Khan and Zaheer Khan and Asif Saeed},

url = {https://link.springer.com/article/10.1007/s10551-022-05181-3},

year  = {2023},

date = {2023-06-01},

journal = {Journal Of Business Ethics},

volume = {185},

pages = {349-374},

abstract = {This paper presents an examination of the relationship between the presence and composition of a corporate social responsibility (CSR) committee on the corporate governance board and CSR decoupling. Using a sample of listed firms drawn from 41 countries, we found that the presence of a CSR committee on the corporate board is negatively associated with CSR decoupling. We also noted that the nature of the industry to which a firm belongs, a firm's level of CSR orientation, and corporate governance quality strengthen such association. Further analysis of the relationship between the structure of the CSR committee and CSR decoupling shows that larger CSR committee size and a greater independence and longer tenure of its members negatively affect CSR decoupling. Our results are robust to various alternative specifications and offer important research and managerial implications. The findings of this study contribute to the growing literature on corporate governance and CSR.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Muhammad Atif; Nazim Hussain
Board gender composition and waste management: Cross-country evidence Journal Article
In: British Accounting Review, vol. 55, no. 1, pp. 101097, 2023.
@article{gull_2638,

title = {Board gender composition and waste management:  Cross-country evidence},

author = {Ammar Ali Gull and Muhammad Atif and Nazim Hussain},

url = {https://www.sciencedirect.com/science/article/pii/S0890838922000269},

year  = {2023},

date = {2023-01-01},

journal = {British Accounting Review},

volume = {55},

number = {1},

pages = {101097},

abstract = {Extant literature on board gender diversity focuses on the main pillars of sustainability while ignoring the important subdimension - waste management. Using a sample of 8365 firm-year observations for the period 2002-2017 from 37 countries, we provide novel empirical evidence that board gender diversity significantly reduces (increases) waste generation (waste recycling) in firms. We also note that the impact is significant with two or more female directors and is primarily driven by female directors' independence. Moreover, the relationship is moderated by the masculinity dimension of national culture and sustainable compensation policies. Our analysis also shows that waste management activities of gender-diverse boards accompany the better financial performance. Our findings are robust to several identification strategies and estimation techniques. Our study provides new insights into the governance-sustainability nexus and presents important policy implications for regulators across countries.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Nazim Hussain; Sana Akbar Khan; Muhammad Nadeem; Alaa Mansour Zalata
Walking the Talk? A Corporate Governance Perspective on Corporate Social Responsibility Decoupling Journal Article
In: British Journal Of Management, vol. 34, no. 4, pp. 2186-2211, 2022.
@article{gull_2634,

title = {Walking the Talk? A Corporate Governance Perspective on Corporate Social Responsibility Decoupling},

author = {Ammar Ali Gull and Nazim Hussain and Sana Akbar Khan and Muhammad Nadeem and Alaa Mansour Zalata},

url = {https://onlinelibrary.wiley.com/doi/full/10.1111/1467-8551.12695},

year  = {2022},

date = {2022-12-01},

journal = {British Journal Of Management},

volume = {34},

number = {4},

pages = {2186-2211},

abstract = {Information asymmetry and the pressure to conform to stakeholders' expectations cause firms to engage in corporate social responsibility (CSR) decoupling - a practice that has severe socioeconomic consequences for firms. Adopting a corporate governance perspective, this paper answers a novel question: whether board gender diversity (BGD) curbs CSR decoupling. Using a battery of sophisticated analyses and robustness tests on 9276 firm-year observations for the period 2002-2017, our results confirm that BGD is negatively associated with CSR decoupling. Analysis of the composition of gender-diverse boards further reveals that this effect is stronger for balanced boards than for skewed and tilted boards. Furthermore, we note that independent female directors are more effective monitors of decoupling than executive female directors. We also document that the relationship between BGD and CSR decoupling is stronger when the overall governance is weak. This implies that gender-diverse boards could act as a substitute mechanism for corporate governance that would otherwise be weak. Our study offers important theoretical and policy implications for the field of corporate governance and CSR.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Sivathaasan Nadarajah; Muhammad Atif; Ammar Ali Gull
State?level Culture and Workplace Diversity Policies: Evidence from US Firm Journal Article
In: Journal Of Business Ethics, vol. 177, pp. 443-462, 2022.
@article{nadarajah_2633,

title = {State?level Culture and Workplace Diversity Policies: Evidence from US  Firm},

author = {Sivathaasan Nadarajah and Muhammad Atif and Ammar Ali Gull},

url = {https://link.springer.com/article/10.1007/s10551-021-04742-2},

year  = {2022},

date = {2022-05-01},

journal = {Journal Of Business Ethics},

volume = {177},

pages = {443-462},

abstract = {This paper examines the effect of state-level culture in the US on the adoption of firms' workplace diversity policies. Using firm-level panel data (1592 firm-year observations) over the period 2011-2014, we document that firms in highly individualistic states are less likely to adopt workplace diversity policies, which in turn negatively affects firm performance. Our results are robust to alternative variables and econometric specifications. Our findings provide insights into the contemporary debate on the economic aspects of workplace diversity policies for firms operating in different cultural backgrounds.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Muhammad Usman; Ammar Ali Gull; Alaa Mansour Zalata; Fangjun Wang; Junming Yin
Female Board Directorships and Related Party Transactions Journal Article
In: British Journal Of Management, vol. 33, no. 2, pp. 678-702, 2022.
@article{usman_2635,

title = {Female Board Directorships and Related Party Transactions},

author = {Muhammad Usman and Ammar Ali Gull and Alaa Mansour Zalata and Fangjun Wang and Junming Yin},

url = {https://onlinelibrary.wiley.com/doi/abs/10.1111/1467-8551.12568},

year  = {2022},

date = {2022-04-01},

journal = {British Journal Of Management},

volume = {33},

number = {2},

pages = {678-702},

abstract = {Using a sample of Chinese firms from 2005 to 2018, we show that firms with female directors (either executive or independent) are characterized by fewer related party transactions (RPTs), particularly in state-owned enterprises. Fewer RPTs are associated with

improved subsequent operating performance and, in contrast, RPTs are associated with

decreased performance for firms with no or fewer female directors, suggesting that female directors engage or allow only efficient but not opportunistic RPTs to facilitate the

long-term strategic objectives of their firms. Our findings are robust for using an alternative measure of RPTs, female board directorships and methods to mitigate potential

endogeneity issues.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Usman Muhammad; Ammar Ali Gull; Alaa Mansour Zalata; Fangjun Wang; Junming Yin
Female Board Directorships and Related Party Transactions Journal Article
In: British Journal Of Management, vol. 33, no. 2, pp. 678-702, 2022.
@article{muhammad_2635,

title = {Female Board Directorships and Related Party Transactions},

author = {Usman Muhammad and Ammar Ali Gull and Alaa Mansour Zalata and Fangjun Wang and Junming Yin},

url = {https://onlinelibrary.wiley.com/doi/abs/10.1111/1467-8551.12568},

year  = {2022},

date = {2022-04-01},

journal = {British Journal Of Management},

volume = {33},

number = {2},

pages = {678-702},

abstract = {Using a sample of Chinese firms from 2005 to 2018, we show that firms with female directors (either executive or independent) are characterized by fewer related party transactions (RPTs), particularly in state-owned enterprises. Fewer RPTs are associated with

improved subsequent operating performance and, in contrast, RPTs are associated with

decreased performance for firms with no or fewer female directors, suggesting that female directors engage or allow only efficient but not opportunistic RPTs to facilitate the

long-term strategic objectives of their firms. Our findings are robust for using an alternative measure of RPTs, female board directorships and methods to mitigate potential

endogeneity issues.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Abid; Ammar Ali Gull; Nazim Hussain; Duc Khuong Nguyen
Risk governance and bank risk-taking behavior: Evidence from Asian banks Journal Article
In: Journal Of International Financial Markets Institutions & Money, vol. 75, pp. 101466, 2021.
@article{abid_2639,

title = {Risk governance and bank risk-taking behavior: Evidence from  Asian banks},

author = {Ammar Abid and Ammar Ali Gull and Nazim Hussain and Duc Khuong Nguyen},

url = {https://www.sciencedirect.com/science/article/pii/S1042443121001724},

year  = {2021},

date = {2021-11-01},

journal = {Journal Of International Financial Markets Institutions & Money},

volume = {75},

pages = {101466},

abstract = {We investigate how risk committee and Chief Risk Officer's characteristics affect the risk-taking behavior of Asian commercial banks in the aftermath of the global financial crisis. Using a sample of 1480 observations representing 185 banks from year 2010 to 2017, we find evidence of a negative and significant link between the risk governance mechanisms and risk-taking. This link is however more pronounced for privately-owned banks (POBs) than for state-owned banks (SOBs). Moreover, risk governance mechanisms positively influence the performance of POBs but have no impact on performance of SOBs. Overall, our results show the role of risk governance mechanisms in curbing excessive risk-taking and improving risk management effectiveness and performance of Asian banks, with some differences across the SOBs and POBs.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Mehdi Nekhili; Ammar Ali Gull; Tawhid Chtioui; Ikram Radhouane
Gender-diverse boards and audit fees: What difference does gender quota legislation make? Journal Article
In: Journal Of Business Finance & Accounting, vol. 47, no. 1-2, pp. 52-99, 2020.
@article{nekhili_2637,

title = {Gender-diverse boards and audit fees: What difference does gender quota legislation make?},

author = {Mehdi Nekhili and Ammar Ali Gull and Tawhid Chtioui and Ikram Radhouane},

url = {https://onlinelibrary.wiley.com/doi/abs/10.1111/jbfa.12409},

year  = {2020},

date = {2020-02-01},

journal = {Journal Of Business Finance & Accounting},

volume = {47},

number = {1-2},

pages = {52-99},

abstract = {We investigate the effect of board (audit committee) gender diversity on audit fees in the French context. We also examine whether the relationship between the proportion of female directors and audit fees is moderated by the enactment of the gender quota law in 2011. We use the system GMM estimation approach on a matched sample of French firms listed in the SBF 120 index between 2002 and 2017. Consistent with the supply-side perspective, we contend that female independent directors and female audit committee members, by improving board monitoring effectiveness, affect the auditor's assessment of audit risk, resulting in lower audit fees. Our findings also document that, by breaking the glass ceiling, the effectiveness of the gender quota law lies not in increasing the proportion of female insider directors, but in boosting the appointment of female independent directors and female audit committee members. Using the difference-in-difference approach, our results reveal that female independent directors and female audit committee members are more willing to assert their monitoring skills after the quota law, leading to lower audit fees. Moving beyond tokenism, we show that, after the quota law, the negative impact on non-audit fees is strengthened only for female independent directors.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Mehdi Nekhili; Haithem Nagati; Tawhid Chtioui
Beyond gender diversity: How specific attributes of female directors affect earnings management Journal Article
In: British Accounting Review, vol. 50, no. 3, pp. 255-274, 2018.
@article{gull_2636,

title = {Beyond gender diversity: How specific attributes of female directors affect earnings management},

author = {Ammar Ali Gull and Mehdi Nekhili and Haithem Nagati and Tawhid Chtioui},

url = {https://www.sciencedirect.com/science/article/abs/pii/S0890838917300513},

year  = {2018},

date = {2018-04-01},

journal = {British Accounting Review},

volume = {50},

number = {3},

pages = {255-274},

abstract = {We apply the system GMM regression estimation approach to a matched sample of French firms listed on Euronext Paris during the period 2001-2010 in order to investigate the relationship between female directors and earnings management by considering their specific (statutory and demographic) attributes. We first find that the presence of female directors deters managers from managing earnings. However, this finding does not hold when the statutory and demographic attributes of female directors are taken into account, thus showing that the detection and the correction of earnings management require particular competencies and skills. Interestingly, we find that business expertise and audit committee membership are key attributes of female directors that promote the effective monitoring of earnings management. An important implication of our findings is that the decision to appoint women on corporate boards should be based more on their statutory and demographic attributes than on blind implementation of gender quotas. Finally, our supplementary analysis reveals that female CEOs and CFOs are strongly inclined to reduce earnings management.},

keywords = {},

pubstate = {published},

tppubtype = {article}

}
Ammar Ali Gull; Muhammad Atif; Ammad Ahmed
Green Strategies and Financial Stability: Unveiling the Impact of Waste Management on Default Risk Conference
International Society for the Advancement of Financial Economics (ISAFE) 2026 Meeting, Beijing International Studies University - Beijing - China, 2026.
@conference{gull_4500,

title = {Green Strategies and Financial Stability: Unveiling the Impact of Waste Management on Default Risk},

author = {Ammar Ali Gull and Muhammad Atif and Ammad Ahmed},

url = {https://isafe2026.sciencesconf.org/?lang=en},

year  = {2026},

date = {2026-06-01},

booktitle = {International Society for the Advancement of Financial Economics (ISAFE) 2026 Meeting},

address = {Beijing International Studies University - Beijing - China},

abstract = {Growing literature focuses on environmental management's positive influence on firm performance; however, the specific link between environmental strategies, particularly waste management, and firm default risk remains unexplored. Our research addresses this gap by empirically examining the relationship between a firm's waste production/recycling practices and its risk of default, using international data spanning 40 countries from 2002 to 2018. Our findings reveal that firms with higher waste generation face increased default risk, whereas those with superior recycling practices exhibit reduced risk. The results hold steady even after accounting for governance mechanisms and the impact of the global financial crisis. We address potential endogeneity issues by employing lagged independent variables, propensity score matching, and a two-stage least squares approach to affirm the robustness of our findings. Our research not only enriches academic discussions on environmental management and corporate risk but also offers practical insights for firms aiming to align environmental and financial objectives.},

note = {25/06/2026 au 27/06/2026},

keywords = {},

pubstate = {published},

tppubtype = {conference}

}
Rizwan Mushtaq; Aitzaz Ahsan Alias Sarang; Ammar Ali Gull; Tanveer Ahsan
Les comités de durabilité ne sont pas toujours efficaces pour responsabiliser les entreprises Miscellaneous
The Conversation, 2024.
@misc{mushtaq_2823,

title = {Les comités de durabilité ne sont pas toujours efficaces pour responsabiliser les entreprises},

author = {Rizwan Mushtaq and Aitzaz Ahsan Alias Sarang and Ammar Ali Gull and Tanveer Ahsan},

url = {https://theconversation.com/les-comites-de-durabilite-ne-sont-pas-toujours-efficaces-pour-responsabiliser-les-entreprises-220696},

year  = {2024},

date = {2024-01-01},

howpublished = {The Conversation},

keywords = {},

pubstate = {published},

tppubtype = {misc}

}
No posts by this author.
